Why Accounting Services Alone Won’t Catch These Q4 Decisions
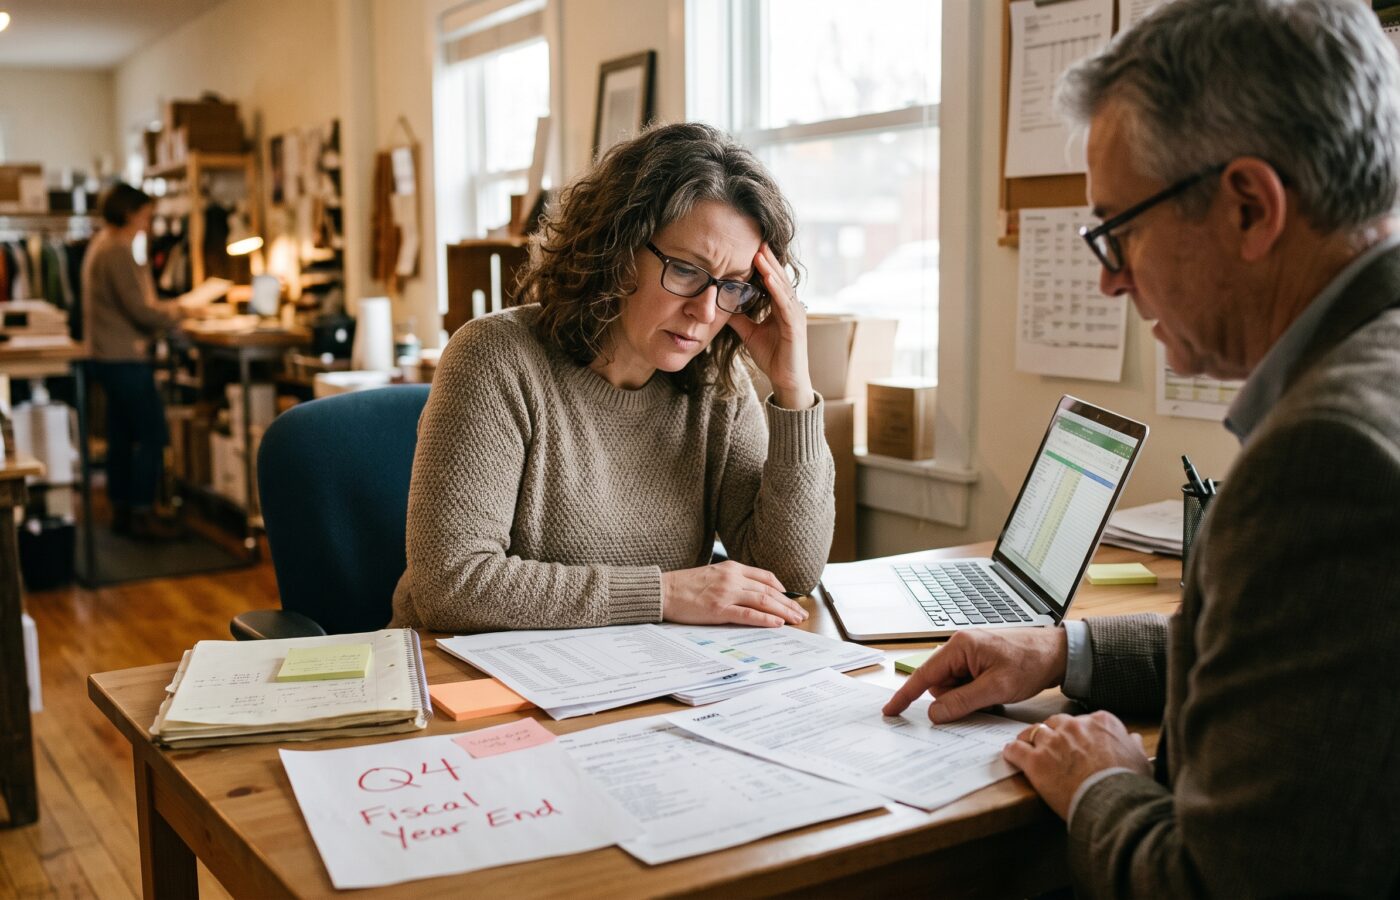
Comprehensive accounting services should do more than record what already happened. Instead, they should actively shape where your business goes next. I have spent more year-end seasons than I can count sitting across the table from confident business owners. Then March arrives, and they realize a few simple decisions back in October could have saved them real money. As a fractional CFO, I usually get the call after the books close and the window for action has passed.
That is not a knock on accountants. In fact, a great accountant is invaluable. However, a clear structural reason explains why traditional accounting services often stop short of the forward-looking advice you need in Q4. So I want to walk you through that gap plainly, the way I would over a cup of coffee in your office.
Accounting services look backward. You need someone looking forward.
Here’s the honest truth about how most accounting services relationships work. First, you hand over receipts, bank statements, and payroll records. Then your accountant reconciles what happened, files the paperwork the law requires, and tells you what you owe. That’s compliance work, and it’s essential. It’s also, by definition, a rearview mirror exercise.
A fractional CFO, on the other hand, does something different. At its core, fractional CFO work is a consulting engagement: advisory, not compliance. In other words, my job isn’t to tell you what already happened to your money. Rather, it’s to tell you what’s about to happen if you don’t change course now, while you still have time. For that reason, Q4 is the most consequential quarter of the year for this kind of forward-looking work. After all, it’s the last window where a decision can still affect this year’s tax bill, this year’s cash position, and next year’s starting line.
Most business owners never hear this from their accountant. The accountant isn’t withholding it, though. Usually, it’s just not part of the engagement. You pay tax preparers to prepare taxes and bookkeepers to keep books. As a result, chances are nobody on that team has a mandate to sit down in September and ask a simple question. Given where we are right now, what should we do differently before December 31st?
That’s the conversation I want to have with you today.
The estimated tax deadline that catches people every single year
Let’s start with something concrete. If you pay quarterly estimated taxes, your fourth quarter payment for the 2026 tax year is due January 15, 2027, according to the IRS. If that date falls on a weekend or holiday, it moves to the next business day. Still, the underlying rule doesn’t change. This is your last chance to true up what you owe before penalties start accruing.
Here’s what most business owners miss, even those with solid accounting services. They calculate their estimated payment from a formula they set back in January. Then they never revisit it, even when the business changes dramatically over the year. For example, maybe revenue came in stronger than expected. Or maybe you had a one-time gain from selling an asset. Either way, your earlier payments may no longer reflect what you actually owe. So if you wait until you file in the spring to find out, you’ll likely face an underpayment penalty. In contrast, a five-minute recalculation in Q4 would have avoided it entirely.
The opposite problem happens too. For instance, I’ve seen business owners overpay all year because a slow first half made them cautious. Then Q3 and Q4 come in strong, and they never adjust their estimate. Essentially, that’s an interest-free loan to the government, sitting in an account you can’t touch until refund season.
Either way, the fix stays the same. Sit down in Q4, before the income period closes on December 31st. Then run an actual projection using this year’s real numbers instead of last January’s guess.
Equipment purchases and the depreciation window nobody explains well
Maybe you’ve been putting off buying equipment, vehicles, software, or other capital assets. If so, Q4 is when that decision starts to matter for your tax bill. The One Big Beautiful Bill restored bonus depreciation to 100 percent for qualifying property. On top of that, the Section 179 deduction limit for 2026 sits at $2,560,000, according to Section179.org. However, the deduction begins to phase out once qualifying purchases exceed $4,090,000 for the year.
Here’s what that means in plain terms. Say you already planned to buy equipment, a company vehicle, or an upgrade to your consulting or technology services tech stack early next year. In that case, making that purchase before December 31st may give you a real advantage. But you must place the asset in service before the deadline, not just order it. Indeed, timing matters more than people assume. For example, I’ve watched clients sign a purchase order in December and assume that was enough. The asset didn’t go into use until February, and consequently that single detail pushed the deduction into the wrong tax year.
Therefore, this decision benefits from a conversation before you buy, not after. Your accounting services team will happily apply the deduction correctly once it’s on the books. What many business owners lack, however, is someone who flags the timing early. That person tells you, in October or November, that moving a planned purchase up could help this year’s numbers.
Retirement contributions: the deadline that isn’t really a deadline
This one surprises people. Say you fund your own retirement through a SEP IRA. The 2026 contribution limit is 25 percent of eligible compensation, up to $72,000, according to Fidelity. Here’s the part that trips people up, though. You generally have until your business’s tax filing deadline to make the contribution. Typically, that deadline is April 15, or October 15 if you file an extension.
So technically, you have more runway than December 31st implies. Even so, I still push clients to decide in Q4. After all, the contribution amount depends on your net income for the year, and you won’t know that number with confidence until you close your books. If you wait until the filing deadline to start thinking about it, you’ll decide under time pressure. Moreover, you often won’t have a clear enough picture of cash flow to know what you can afford to set aside.
Deciding in Q4 gives you breathing room, even if the money doesn’t move until spring. As a result, you can plan the contribution around your actual cash position instead of scrambling for funds in April. It also lets you weigh whether a Solo 401(k) might serve you better than a SEP IRA. The two plans follow different rules for what counts toward the limit and how contributions interact with your compensation. Ultimately, that conversation belongs with someone who understands your full financial picture, not just your tax return.
The cash flow conversation most accounting services skip
Here’s where I probably differ most from a traditional accounting services engagement. Taxes are one input into your business’s health. However, they’re not the whole picture, and they’re usually not the most urgent one.
In Q4, I ask clients questions that have nothing to do with the IRS. For example, what does your cash position look like heading into a slower January and February? Do customers still owe you money from earlier in the year? Is inventory sitting on shelves, tying up cash you’ll need for payroll in six weeks? And what will next year’s fixed costs actually be, given new hires, lease renewals, or contracts you’ve already signed? Questions like these sit right where finance meets what operations management actually covers day to day.
None of that shows up on a tax return. Yet all of it determines whether you start next year strong or scrambling. A good bookkeeper can tell you your cash balance today. By contrast, a fractional CFO builds a forecast that shows what it will be in March. Then we flag the gap while you still have time to close it.
So ask your current accounting services provider one question. Do they offer any forward-looking cash forecasting, or is everything historical? There’s no shame in the answer being no. In fact, most accounting engagements focus on compliance, not forecasting, because the two require different skill sets. Still, you deserve to know which one you’re getting.
A real example of what falls through the cracks
Here’s a real example, with the details changed. A client of mine ran a services business that looked healthy on paper all year. Revenue was up, the accounting services team had good news at every check-in, and the owner felt confident heading into Q4. However, nobody had modeled one thing. Three large invoices all came due in the same thirty-day window. Together, they equaled almost two months of payroll. Worse, they landed right alongside a lease renewal, a slower seasonal stretch, and a tax payment.
None of those facts was a secret. Nobody, however, had ever laid them side by side on a single timeline. Once we did, the fix was simple. First, we renegotiated two payment terms. Then we delayed a planned hire by six weeks. After all, hiring plans deserve the same scrutiny as cash flow, and staffing and workforce plans often quietly fall apart by Q2 when nobody revisits the assumptions. Neither move would have been obvious from a profit and loss statement, because that statement doesn’t show you when cash actually moves.
In short, that’s the difference between knowing your numbers and knowing your timing. Most business owners have the first. Very few, however, have someone actively managing the second.
Reasonable compensation and entity structure, before it’s too late to matter
If you run an S corporation, Q4 is the time to review your reasonable compensation. The IRS expects S corp owners who work in the business to pay themselves a fair market salary. The remaining profit then goes out as distributions. So if you set that salary too low, you’re exposed if the IRS takes a second look. On the other hand, set it too high, and you’ll pay more in payroll taxes than you need to.
This matters in Q4 for a simple reason. Payroll adjustments in November or December can still meaningfully affect the year’s totals. In contrast, fixing compensation after the year closes puts you in a much weaker position. More than one client has discovered this in tax season. Their salary-to-distribution split had drifted out of a defensible range during a busy year, because nobody was checking it as circumstances changed.
Likewise, your entity structure deserves the same attention. Maybe your business grew or changed shape this year. Perhaps revenue crossed a new threshold, you added partners, or you took on outside investment. If so, Q4 is the natural moment to ask whether your current structure still fits. These aren’t quick fixes for the last week of December. That’s exactly why they belong on the table now, not in April.
What accounting services should actually include, and where the gap usually is
I want to be fair here, because I don’t think most accountants are dropping the ball. Rather, the industry has quietly narrowed what accounting services means for many small and midsize businesses. As a result, compliance work and strategic advisory became two separate jobs, and nobody announced the split.
If your provider covers bookkeeping, tax preparation, and filing, that’s a complete and valuable service on its own terms. Still, apply the same scrutiny you’d give any other vendor. For example, it pays to know what a marketing agency actually bills for before assuming a retainer covers more than it does. The same goes for your accounting services. Here’s what the engagement typically doesn’t include, unless you’ve asked and paid for it: someone who watches your numbers all year and tells you, unprompted, “here’s a decision you should make in the next six weeks.”
That’s the gap a fractional CFO fills. However, the goal isn’t to replace your accountant. Instead, it’s to sit alongside them and turn their historical numbers into forward decisions about hiring, pricing, cash reserves, and tax timing. Proactive monitoring adds the same value anywhere in a business. In fact, it’s the principle behind catching recurring help desk tickets before they harden into a pattern nobody questions. Accordingly, my best working relationships involve close coordination with the client’s existing accounting team, not a turf war.
What I’d actually ask my accountant this quarter
If you take nothing else from this, bring these questions to whoever handles your books:
- What’s our year-to-date net income, and how does it compare to our original projection?
- Based on that, what should our Q4 estimated payment actually be?
- Should we move up any planned equipment or asset purchases before December 31st?
- What’s our current reasonable compensation split, and should anything this year change it?
- Is anyone forecasting our cash flow into next year, or is everything we see historical?
Clear, confident answers to those questions mean you’re in good hands. A pause followed by “let me look into that,” however, tells you something important. Specifically, you’ve found where the gap in your financial picture sits, and what a fractional CFO conversation would add.
The bottom line on accounting services and Q4
Your accountant isn’t hiding anything from you. They’re doing the job you hired them to do. That job, however, is almost always backward-looking and compliance-focused, and doing it well is valuable. But Q4 is a forward-looking quarter. Therefore, you have to make the decisions that move the needle on taxes, cash, compensation, and next year’s starting position before the calendar turns. That kind of proactive checkpoint reflects the same discipline behind any general business strategy built on repeatable habits instead of a single annual document.
So if you’ve read this far and realized nobody in your corner asks these questions proactively, fix that before December 31st arrives.
None of this requires firing your accountant or overhauling your accounting services. In fact, in most of my engagements, the accounting team stays exactly where they are. They keep doing what they already do well, and I add the forward-looking layer on top. In other words, the two roles aren’t in competition. They solve different problems on different timelines. As a result, a business with both working together tends to walk into January with a plan instead of a surprise.
So here’s my advice, plain and simple. Don’t wait for your tax preparer to bring this up, because it may not be part of what you hired them to do. Instead, bring it up yourself, this month, while you still have runway to act on the answers.
Frequently Asked Questions
When are Q4 2026 estimated tax payments due?
The fourth quarter estimated tax payment covers income earned between September 1 and December 31, 2026. It’s due January 15, 2027, per the IRS estimated tax FAQ. However, if that date falls on a weekend or holiday, the deadline shifts to the next business day.
What is the Section 179 deduction limit for 2026?
The 2026 Section 179 deduction limit is $2,560,000. However, the deduction begins to phase out once total qualifying purchases exceed $4,090,000 for the year. Section179.org has the full details.
Is bonus depreciation still available in 2026?
Yes. The One Big Beautiful Bill Act restored bonus depreciation to 100 percent for qualifying property. You can review the mechanics in this IRS guidance on the additional first year depreciation deduction.
Can I still contribute to a SEP IRA for the 2026 tax year after December 31st?
Generally, yes. You can make SEP IRA contributions up to your business’s tax filing deadline, typically April 15, or October 15 with an extension. The 2026 limit is 25 percent of eligible compensation, up to $72,000. For the full rules, see Fidelity’s SEP IRA contribution guide.
What’s the difference between accounting services and fractional CFO services?
Accounting services typically cover bookkeeping, tax preparation, and compliance filing. In other words, they look at what already happened financially. Fractional CFO services, by contrast, are a form of financial consulting focused on what comes next, including cash flow forecasting, tax timing, pricing, and financial planning. Many businesses benefit from both, working together rather than one replacing the other.
Do I need a fractional CFO if I already have accounting services?
It depends on what you need. If your current provider already offers proactive forecasting and strategic planning, you may not need extra support. However, if you only get historical reporting and tax compliance, a fractional CFO can help. It fills the forward-looking gap without replacing the accounting work you already rely on.
How is reasonable compensation determined for S corporation owners?
The IRS expects S corp owner-employees to pay themselves a salary that reflects fair market value for their role. That figure depends on training, experience, time devoted to the business, and what comparable roles pay in the same industry and region. Typically, the IRS compares that salary to what the business distributes. Therefore, adjusting it before year-end, rather than after, gives you more flexibility.
References
- Internal Revenue Service. Estimated Tax. https://www.irs.gov/faqs/estimated-tax
- Internal Revenue Service. Treasury, IRS issue guidance on the additional first year depreciation deduction amended as part of the One, Big, Beautiful Bill. https://www.irs.gov
- Section179.org. 2026 Section 179 Deduction: Limits, Phase Outs & Examples. https://www.section179.org
- Fidelity. SEP IRA contribution limits for 2025 and 2026. https://www.fidelity.com
- Kiplinger. Estimated Tax Payment Deadlines 2026: Quarterly Due Dates and How to Avoid IRS Penalties. https://www.kiplinger.com
- NerdWallet. Estimated Tax Payments: How They Work and 2026 Due Dates. https://www.nerdwallet.com
- Journal of Accountancy. Tax news and information. https://www.journalofaccountancy.com